What happened
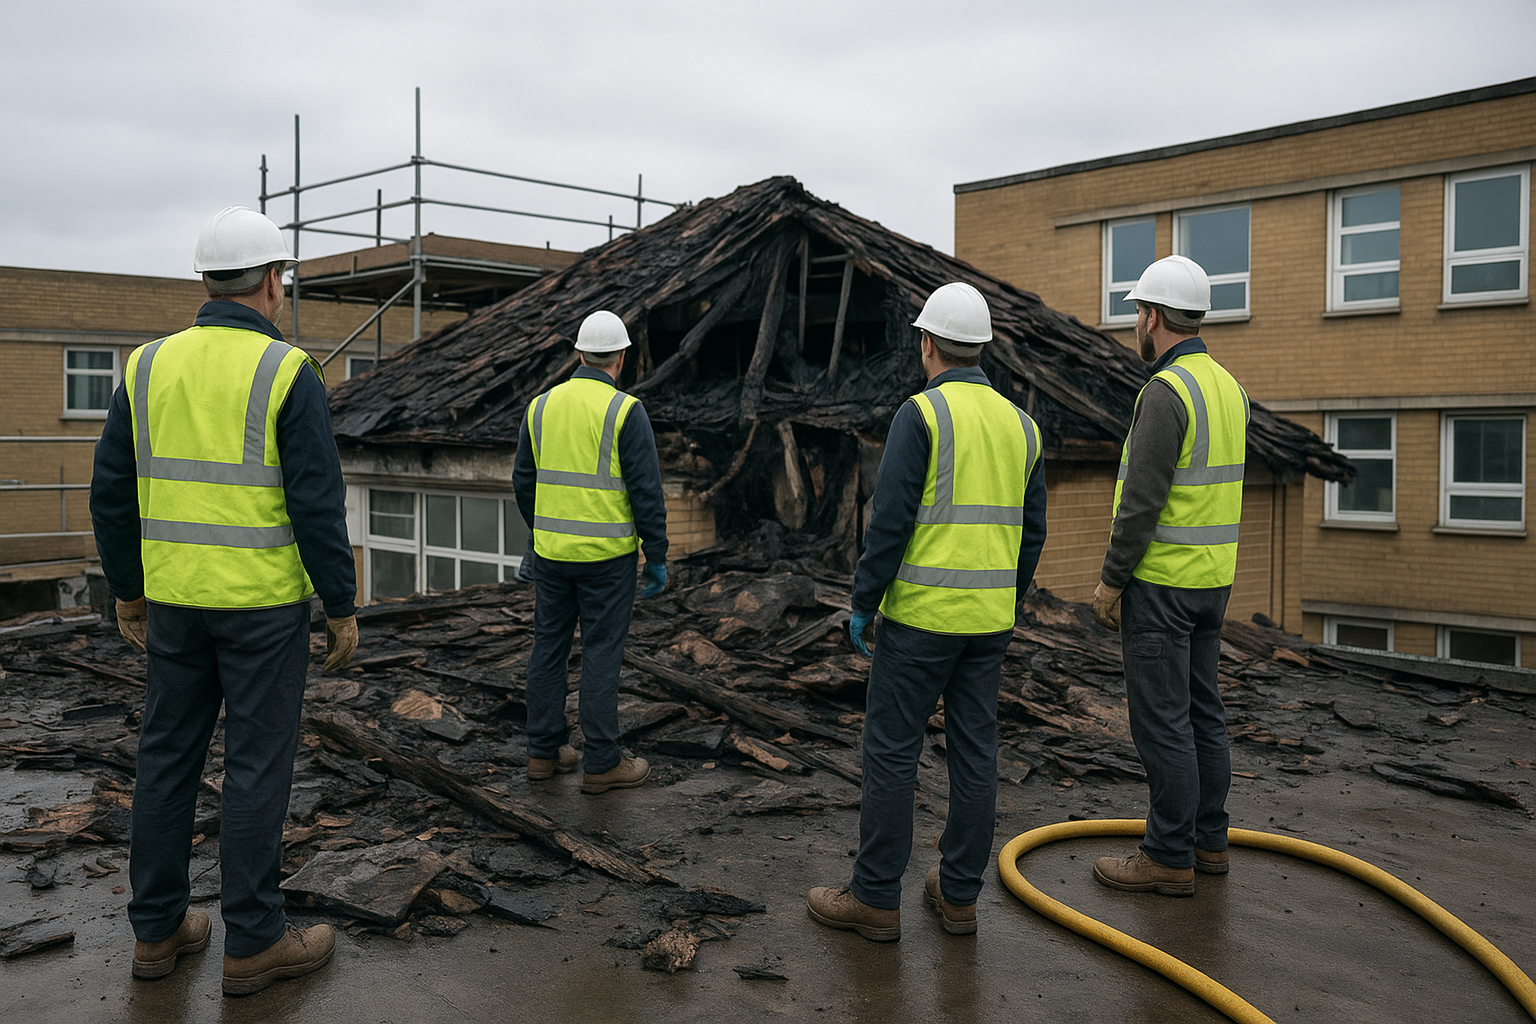
Attleys Roofing, a contractor based in Banbury, faced a High Court dispute with its insurer QBE after a major fire at Horris Hill Preparatory School in Newbury on 27 April 2023. The firm was working with an oxyacetylene torch on roof lead detailing shortly before a blaze broke out, severely damaging the roof of a three-storey building known as the Bank. More than 50 firefighters attended the scene, and the fire alarm was triggered just after the workers left at around 11.40am. The exact origin of the fire remains undetermined, but Attleys states it started in or around the roof area.
After the incident, both the freeholder and leaseholder of the property submitted provisional compensation claims totalling £3.1m. Attleys denies any breach of fire-safety procedures or responsibility for causing the fire. The company sought confirmation from its insurer, QBE, that its policy would cover any liabilities and legal costs related to the incident. However, QBE disputed the claim, citing conditions in the policy that were not met.
The background
The dispute centres on specific fire-safety precautions set out in Attleys' insurance policy with QBE. The policy listed steps the contractor had to follow when performing work with naked flames or heat sources. These included appointing someone for fire safety, checking for combustibles within a six-metre radius, ensuring extra monitoring during works, and keeping a continuous fire watch for an hour after finishing the work.
Attleys claims it followed these measures and maintains it did not act negligently or recklessly, as set out in its Particulars of Claim dated 7 July 2025. QBE, however, refused to confirm cover on 20 June 2024, arguing that even an accidental failure to meet any of these listed precautions could void cover.
Without insurance, Attleys warned in court documents that legal costs and any compensation could be high enough to destroy the business, which has traded as a family run firm for around 40 years and does not file audited accounts.
What people are saying
During the High Court hearing, Attleys argued that the policy requirement to take “reasonable precautions” would mean a breach only where the contractor acted recklessly. The contractor emphasised that QBE had not made any allegation of reckless behaviour by Attleys or its staff. The company also denies any breaches of the fire-safety policy or negligence in respect of the incident.
QBE's position was that the detailed precautions in the policy were absolute requirements. It stated that failing to follow them, whether deliberately, negligently, or even innocently, could invalidate the insurance. Judge Pearce accepted QBE’s arguments, noting that although insurance clauses about "reasonable precautions" usually focus on reckless conduct, this policy's explicit safeguards went further.
The judge ruled that the insurance created "an absolute obligation to take the precautions specified", and this meant a negligent or innocent failure would still be enough to prevent any pay-out for the contractor. The judge noted the court was only deciding how the policy should be interpreted, not yet made a finding about whether Attleys actually breached any of the requirements or was responsible for the fire.
What happens next
The High Court ruling handed down on 26 October clarifies only the legal interpretation of the policy wording. Whether Attleys in fact breached policy terms, and whether this should block any pay-out for the fire, will be dealt with in a further hearing. A decision date has not been specified in the judgment.
Even if the court later finds Attleys failed to meet one or more of the required fire-safety steps, an additional legal question remains. Under section 11 of the Insurance Act 2015, the firm can argue that the failure did not "increase the risk" of the loss that occurred. This point is likely to be considered as proceedings continue.
In the meantime, Attleys faces ongoing uncertainty. The provisional claims for compensation and the possible legal costs arising from the blaze, if not covered by insurance, may place the firm in a financially precarious situation, as stated in court documents.
The numbers
The loss arising from the fire is estimated at £3.1m based on provisional compensation claims filed by the school’s freeholder and occupiers. More than 50 firefighters attended the blaze, which damaged the roof of a three-storey building. Attleys, a family business trading for almost 40 years, reports that these liabilities could potentially "destroy" the firm if insurance cover is refused.