Brick deliveries and stocks
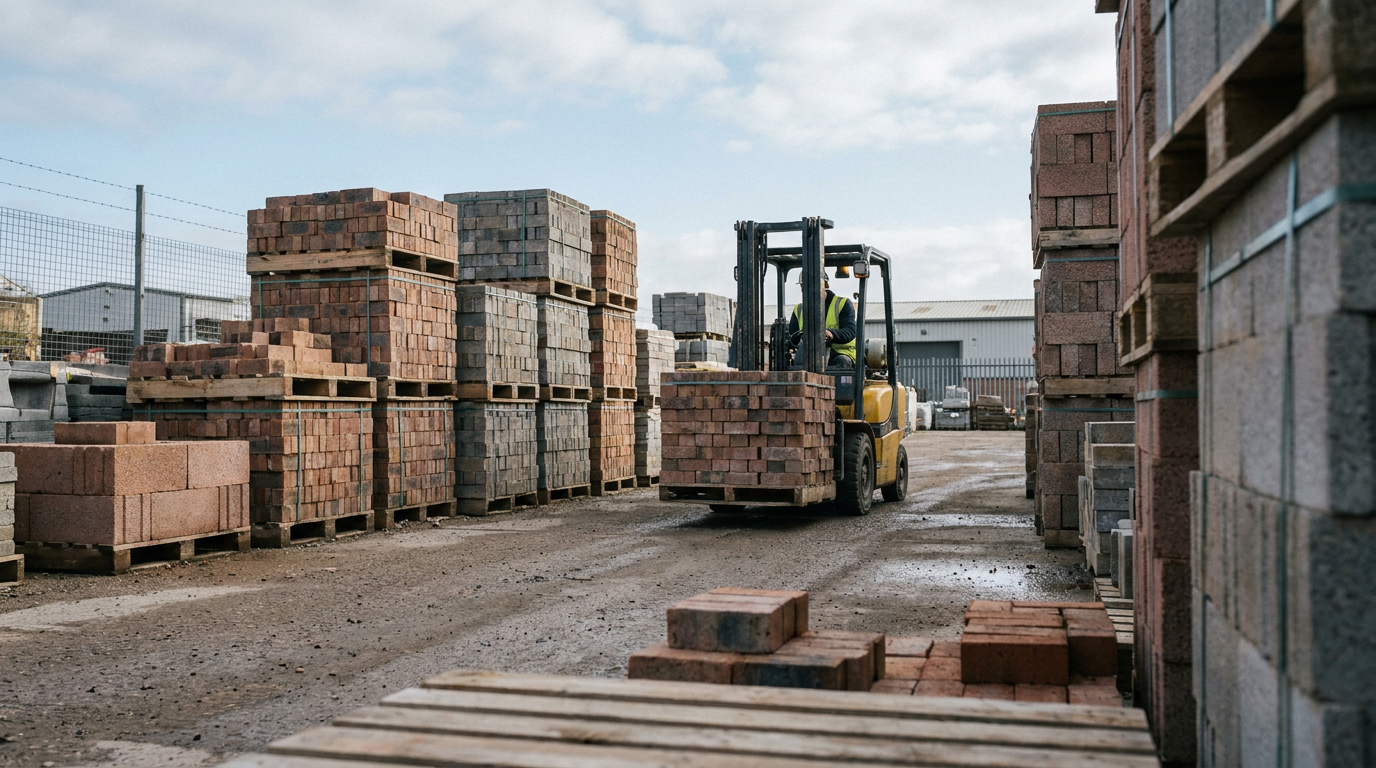
Government figures reported by Construction News put seasonally adjusted brick deliveries at 95.4 million in July, against 123.5 million in July 2025. Deliveries were also 10% below June’s level.
The monthly fall followed an annual decline in June, when deliveries were 17.6% lower than a year earlier. July’s figures therefore showed a larger year-on-year reduction as well as a further monthly drop.
Brick production also fell, but stocks remained above their year-earlier level. Total output was 110.7 million bricks in July, down 16.3% annually. Stocks stood at 541 million at the end of the month, an increase of 16.1%.
Material prices
The decline in brick activity came alongside further increases in construction material prices. The all-work materials price index was 5.9% higher in July than a year earlier. It also rose by 0.4% during the month.
Annual price increases differed across categories of work. Materials used in other new work rose by 7.2%, compared with 5.5% for repair and maintenance. The increase for new housing materials was 4.9%.
Fabricated structural steel recorded the largest annual price rise among individual materials, at 20.9%. Rigid pipes and fittings increased by 15.5%, while flexible pipes and fittings rose by 11.7%.
Not every material category became more expensive. Cement prices were 3.5% lower than a year earlier, while electric water-heater prices fell by 1.5%.
Concrete products and roofing tiles
Concrete block deliveries showed a smaller annual decline than bricks. Seasonally adjusted deliveries totalled 3.98 million square metres in July, down 10.8% year on year. The monthly change was more limited, with deliveries 0.2% below June.
Ready-mixed concrete sales moved in different directions depending on the comparison period. Seasonally adjusted sales reached 2.59 million cubic metres in the second quarter. That was 6.1% below the same quarter of 2025 but 1.5% above the first quarter.
Seasonally adjusted sand and gravel sales also fell. They were 9.2% lower than a year earlier and 3% below the preceding quarter.
Concrete roofing tiles differed from the other materials indicators. Second-quarter production reached 6.88 million square metres, an annual increase of 77.7%. Deliveries rose by 52.1% to 6.13 million square metres.
Those tile increases were measured against particularly low production and delivery volumes in the second quarter of 2025. That comparison forms part of the context for the annual growth figures.
Housebuilding outlook
Noble Francis, economics director at the Construction Products Association, linked the brick figures to conditions in housebuilding. Writing on X, he described deliveries as an indicator of new housing starts. He said July’s decline was consistent with weaker housing output as higher mortgage rates began to affect activity.
Francis said housebuilders were continuing work on existing developments while changing their build rates to match subdued and slowing demand. He said new developments were generally not being started, apart from a few exceptions on selected sites.
He also cautioned that annual comparisons could become less negative later in 2026. Activity in autumn 2025 had been depressed by speculation about Budget-related tax changes, he said. His expectation for the later figures reflected that weaker comparison period.